If you want to know how long your retirement savings will really last, inflation changes the answer immediately. A fixed dollar withdrawal may feel stable, but its spending power falls as prices rise; an inflation-adjusted withdrawal protects your lifestyle goal better, but it also asks more from the portfolio over time.
In this source set, we can show how common withdrawal-rate guidance works, why inflation raises the pressure, and why early bad returns can make the damage permanent. We cannot quantify the effect of fees here, because the provided sources do not include fee data or fee examples.
What are the common retirement withdrawal benchmarks?
The best-known benchmark is the 4% rule. CNBC reported that the rule was developed by financial planner William Bengen in the 1990s and became a benchmark for retirement withdrawal rates, with a hypothetical retiree who has $1 million at age 65 taking an initial $40,000 withdrawal under that approach in year one (CNBC).
The mechanics are straightforward in the sources we have. The Retirement Budget Calculator says the 4% rule means withdrawing 4% of the initial portfolio in year one and then adjusting that amount for inflation each year (Retirement Budget Calculator).
But 4% is no longer the only common reference point. CNBC reported that in December, Morningstar said 3.9% is the highest starting safe withdrawal rate for retirees (CNBC). The Retirement Budget Calculator also says many experts now suggest 3% to 3.5% for longer retirements and lower expected returns (Retirement Budget Calculator).
At the same time, CNBC reported that Morningstar said retirees can withdraw up to 5.7% of their starting portfolio if they use a more flexible approach, according to its 2025 State of Retirement Income report (CNBC). That is not the same thing as saying everyone can safely spend 5.7% with no tradeoffs. The tradeoff is flexibility: the reported higher starting rate depends on not treating spending as fixed in every market environment.
| Approach mentioned in sources | Starting rate | How the sources describe it | What it implies |
|---|---|---|---|
| Classic 4% rule | 4% | Withdraw 4% of the initial portfolio in year one, then adjust for inflation each year (Retirement Budget Calculator) | Simple rule of thumb; on $1 million, the cited first-year withdrawal is $40,000 (CNBC) |
| Morningstar starting safe rate | 3.9% | CNBC says Morningstar called this the highest starting safe withdrawal rate for retirees in December (CNBC) | Lower starting income than 4%, but framed as safer |
| More conservative planning range | 3% to 3.5% | Many experts now suggest this for longer retirements and lower expected returns (Retirement Budget Calculator) | Builds in more caution |
| Flexible spending approach | Up to 5.7% | Morningstar said retirees can withdraw up to 5.7% of their starting portfolio with a more flexible approach (CNBC) | Higher starting income, but not with a fixed-spending promise |
One more point matters here: CNBC also reported an interpretation that a 4% starting withdrawal with annual inflation adjustments has often been too weak across many historical market periods, leaving people with large leftover balances because it encouraged them to underspend (CNBC). That does not mean 4% is “wrong.” It means a simple rule can be conservative in some periods and still feel stressful in others, especially when inflation and market returns do not cooperate at the same time.
Why does a fixed retirement withdrawal lose spending power?
The key distinction is between nominal dollars and spending in today’s dollars. The Retirement Budget Calculator says monthly living expenses in today’s dollars are the amount needed after taxes, and that spending increases each year by the inflation rate (Retirement Budget Calculator).
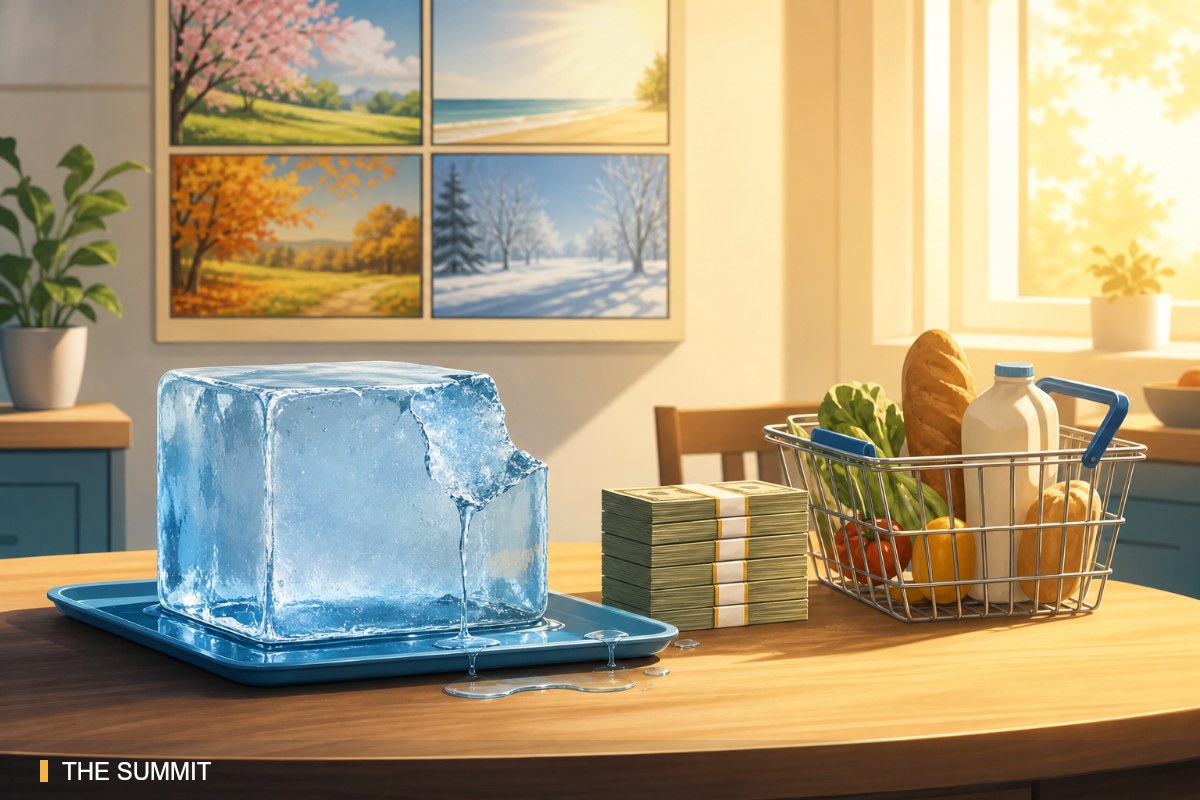
That sentence carries most of the real-life problem. If you retire and keep taking the same dollar amount every year, your withdrawal does not rise with inflation. Your bank transfer may look unchanged, but the amount of groceries, housing, transportation, healthcare, and other essentials it buys can shrink.
By contrast, if you increase your withdrawal each year by inflation, you are trying to preserve the same standard of living in today’s dollars. That is the logic behind the 4% rule framework described by the calculator: take 4% in year one, then adjust that amount upward for inflation each year (Retirement Budget Calculator).
This is the central tradeoff:
- A fixed nominal withdrawal is gentler on the portfolio but harsher on your lifestyle over time.
- An inflation-adjusted withdrawal is gentler on your lifestyle target but harsher on the portfolio over time.
The sources also note that non-portfolio income can change the math. The Retirement Budget Calculator says pension income, rental income, part-time work, or annuity payments are also inflated each year at the inflation rate and reduce the amount you need to withdraw from the portfolio (Retirement Budget Calculator). In practical terms, the more of your spending that is covered by outside income, the less exposed your portfolio is to inflation-driven withdrawal increases.
What does recent inflation evidence say about the pressure on retirees?
The cleanest number in the source set comes from the Federal Reserve. It said that between October 2013 and September 2025, price levels increased by 35% based on the Chained Consumer Price Index (Federal Reserve, Savings and Investments).
For retirement planning, that is the pressure point. If your spending goal was defined in today’s dollars at retirement, and prices later rise substantially, maintaining the same real lifestyle requires larger nominal withdrawals.
The Federal Reserve also said median household income from 2013 to 2024 rose 56% in nominal terms and 20% after adjusting for inflation (Federal Reserve, Savings and Investments). That is useful context, but retirees should be careful with it. Household income growth is not the same thing as retirement portfolio growth, and it is not the same thing as the income growth an individual retiree can count on once work earnings stop.
So the practical consequence is narrower than a headline about “income rose” might suggest. In retirement, the important question is not whether household income rose somewhere in the economy. It is whether your withdrawal plan and any non-portfolio income sources can keep up with rising prices without exhausting savings too quickly.
What the $40,000 example does—and does not—tell you
The most concrete illustration in the sources is the CNBC example: a retiree with $1 million who uses the 4% rule would start by withdrawing $40,000 at age 65 (CNBC).
What it tells you:
- Your first-year withdrawal is a starting point, not a full answer about sustainability.
- If you follow the inflation-adjusted 4% framework, later withdrawals are meant to rise with inflation, not stay flat (Retirement Budget Calculator).
- If inflation is meaningful over a long stretch, the dollar amount you need later can be much higher than the initial $40,000.
What it does not tell you:
- How fund or advisory fees would compound against the portfolio over 10, 20, or 30 years, because that data is not provided here.
- How your own taxes, spending categories, or investment returns would change the outcome, because those figures are not provided here.
Why can retirement balances be harder to judge than they look?
Readers often compare their retirement readiness to a single published account balance figure. That can be misleading. The Federal Reserve says the Survey of Consumer Finances provides detailed estimates of the types of assets and liabilities held by U.S. households and the value of their holdings (Federal Reserve, Savings and Investments).
The practical implication is that household retirement readiness is often spread across multiple buckets rather than one visible account snapshot. A brokerage balance, a workplace plan, cash savings, rental income, or another asset may all matter when estimating how much pressure lands on the portfolio.
If you want a separate benchmark on balances by age, our editorial team also broke down median retirement savings at ages 65 to 74. But even then, balance snapshots alone do not solve the inflation problem. A balance can look large in nominal dollars and still support less spending power than expected.
What is a simple way to think about retirement depletion risk?
A practical framework from these sources is to test your plan in layers instead of chasing one “magic” withdrawal rate.
1) Start with the spending target in today’s dollars
The Retirement Budget Calculator says living expenses should be framed in today’s dollars after taxes and then increased each year by inflation (Retirement Budget Calculator). That means your real target is a lifestyle, not a fixed number on an annual statement.
2) Identify how much of that target is covered without selling investments
The same source says pensions, rental income, part-time work, and annuity payments reduce needed withdrawals from the portfolio and are also inflated each year at the inflation rate (Retirement Budget Calculator). The more reliable income you have outside the portfolio, the less inflation-adjusted pressure your investments have to carry.
3) Choose a withdrawal style, not just a rate
The source set points to at least three styles:
- Classic rule-based spending: start at 4% and adjust annually for inflation (Retirement Budget Calculator).
- Lower starting rate: consider 3.9% or even 3% to 3.5% when the goal is more conservatism, as reported by CNBC and the Retirement Budget Calculator (CNBC; Retirement Budget Calculator).
- Flexible spending: start higher only if you are willing to adjust spending, with CNBC reporting Morningstar’s figure of up to 5.7% under a more flexible approach (CNBC).
If you want to think through which accounts you would actually tap first once withdrawals begin, our related guide on retirement withdrawal order can help with that operational side.
4) Stress-test the early years
The Retirement Budget Calculator says sequence-of-returns risk is the danger that poor investment returns in the early years of retirement permanently damage a portfolio, even if later returns are above average (Retirement Budget Calculator).
This matters because inflation and market losses can compound each other in the worst direction. If prices rise and you raise withdrawals to keep up, but the portfolio is simultaneously hit by weak early returns, you may be selling more assets at lower values. That is one reason a retirement balance can run out sooner than a simple average-return assumption would suggest.
5) Remember that a “successful” plan can still feel too tight—or too loose
CNBC reported the interpretation that the 4% rule has often been too weak across many periods, leaving large leftover balances because retirees underspent (CNBC). That is a useful reminder that there are two planning failures, not one:
- Running out too early.
- Living too cautiously and never using money that was available to improve life.
That is why flexibility matters. A rule can guard against depletion risk, but your lived experience depends on how inflation, returns, and your willingness to adjust spending interact.
What can’t this evidence answer about fees and current balances?
Two limits are important.
First, this source set does not provide fee data, fee examples, or a fee model. So while the reader question includes fees, we cannot document how much annual fund or advisory fees would reduce a portfolio over 10, 20, or 30 years from the evidence here.
Second, the source set does not provide current retirement-savings balance figures that would let us estimate how much cushion households broadly have right now. We can say the Federal Reserve’s Survey of Consumer Finances is designed to measure the types and values of household assets and liabilities (Federal Reserve, Savings and Investments), but we cannot plug in a current median or average figure from the materials provided.
That means the most defensible takeaway here is narrow but useful: inflation can erode the spending power of a fixed retirement withdrawal, inflation-adjusted withdrawals ask more from the portfolio over time, and early poor returns can make the gap worse. If you are reviewing your first retirement-income plan, it helps to separate spending needs in today’s dollars from the nominal dollar amount you happen to withdraw this year.
FAQ
What withdrawal rates are commonly used in retirement planning?
The best-known benchmark is the 4% rule, which CNBC says was developed by William Bengen in the 1990s and became a common reference point (CNBC). CNBC also reported that Morningstar said 3.9% is the highest starting safe withdrawal rate for retirees, while the Retirement Budget Calculator says many experts now suggest 3% to 3.5% for longer retirements and lower expected returns (CNBC; Retirement Budget Calculator). For people willing to be flexible, CNBC reported Morningstar’s figure of up to 5.7% of the starting portfolio (CNBC).
How does inflation affect a fixed retirement withdrawal?
The Retirement Budget Calculator says retirement spending should be measured in today’s dollars and increased each year by the inflation rate, and that the 4% rule adjusts withdrawals for inflation annually (Retirement Budget Calculator). The Federal Reserve said price levels rose 35% between October 2013 and September 2025 based on the Chained Consumer Price Index (Federal Reserve, Savings and Investments). So a fixed nominal withdrawal buys less over time when prices rise.
Why can a retirement portfolio run out sooner than expected?
One reason is sequence-of-returns risk. The Retirement Budget Calculator says poor investment returns in the early years of retirement can permanently damage a portfolio even if later returns are above average (Retirement Budget Calculator). CNBC also reported the interpretation that some retirees may underspend under a rigid 4% rule, which shows that a rule can miss in both directions depending on market history and spending flexibility (CNBC).
Do published retirement balance snapshots capture everything households may have saved?
Not necessarily. The Federal Reserve says the Survey of Consumer Finances provides detailed estimates of the types of assets and liabilities held by U.S. households and the value of those holdings (Federal Reserve, Savings and Investments). That means retirement readiness may be spread across several assets rather than one account balance alone.
Sources
- Does the 4% retirement rule still work? New research points to another strategy to maximize income — CNBC, 2026-07-29
- Free Retirement Calculators (2026) — Retirement Budget Calculator, 2026-10-31
- Savings and Investments — Board of Governors of the Federal Reserve System, 2026-05-26
This article is for educational purposes only and is not personalized financial, tax or legal advice. Rules and figures change; check the linked official sources or a qualified professional before acting.
Not financial advice. This article is for educational purposes. Consider your own situation or speak with a licensed advisor before making financial decisions.